Worried about your mortgage? Don’t panic!
With interest rates on the rise home payments can be a worry, but expert Martyn James has a secret weapon
I’m regularly contacted by readers who are worried about paying their bills, and one of their biggest concerns is mortgages. The Bank of England recently raised the base rate of interest to 4 per cent and hinted that more rises may happen. Now the news is filled with stories of rising remortgage rates and first-time buyers being priced out of the market.
However, I’m not here to ruin your Christmas. Unlike Scrooge, mortgage companies don’t want you to struggle and default on your mortgage. In fact, there are a range of options out there for you if you are due to renew your mortgage in the coming year.
But don’t take my word for it! I’ve drafted in my good mate and fellow television expert Sarah Tucker, AKA The Mortgage Mum, to share her tips with you all.

Get help before your mortgage comes up for renewal
“Giving yourself time to discuss your fears and worries will help your broker understand more about your financial situation so they can find the best possible outcome for you, taking everything into account," says Sarah. “They’ll understand your needs and can use their expertise to find you the best deal, help you manage the situation or give you breathing space.”
“Your broker will check rates continuously until completion. So even if you’ve settled for a ‘worst case scenario rate’, you can still take advantage of better rates that come along in the run-up to your remortgage. A lot can happen in the market in just a month, so the rates you see today are not set in stone or destined to get worse”.
What about tracker mortgages?
Tracker rates can often be cheaper than fixed rate deals, but that’s because of the risk of the rates going up as they “track” the Bank of England base rate. Sarah says that many clients are seeking tracker mortgages to get the cheapest deal. However, some lenders have added an early repayment charge in some cases for getting out of the deal early, which isn't the flexibility a tracker rate usually offers.
What if I can’t afford my mortgage?
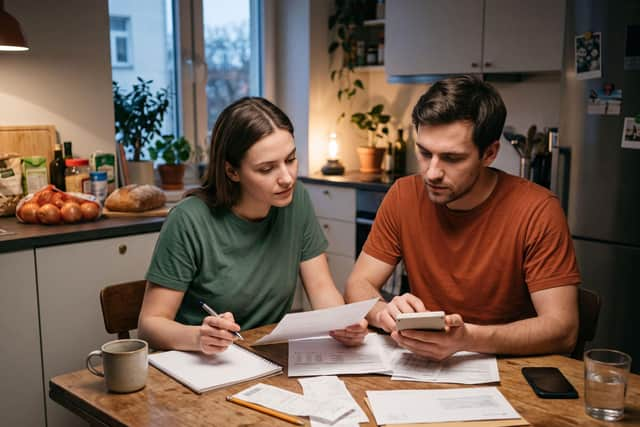
If your mortgage is on the horizon, then it makes sense to make a detailed budget, covering all your bills and expenses. Factor in food, transport and leisure too. This should give you an idea of what you can afford – and highlight if you need help. You may also spot some areas where you can make savings too.
There are lots of options available to mortgage lenders if you can’t pay your mortgage. This could involve mortgage “holidays” if you need a few months of breathing space, or extending the term of your agreement. You could also go on to an interest-only mortgage, though you won’t be paying any money off the cost of your actual home if you do this.
There are even options for people in dire circumstances, so don’t assume you won’t get help. The worst thing you can do is go into denial. That’s when arrears get so high there’s no going back.
I’m a first-time buyer – help!
The government's new First Homes Scheme is coming and it's created a bit of excitement. Under the scheme you may be able to buy a home for 30 per cent to 50 per cent less than its market value. But that’s not the only option. Here are Sarah’s tips:
- Don’t wait until you’ve got the cash. Speak to a broker or adviser today even if you are years off a mortgage – and don’t use AI or search drives for advice!
- You may find that there are simple changes you can make to your lifestyle and spending – particularly if you are self-employed – that will improve your chances.
- Avoid taking out too much credit in the run-up to a mortgage application. Buy now, pay later deals are starting to feature on credit files. So keep your borrowing low or clear your credit and loan payments each month. Check your credit files too!
Martyn James is a leading consumer rights campaigner, TV and radio broadcaster and journalist. Read more articles by Martyn by clicking on this highlighted link.
Comments
Want to join the conversation? Please or to comment on this article.