Floating wind ambitions depend on certainty
The UK has everything that’s needed to get a lucrative new energy industry going. Well, almost, says Niamh Deery
The UK is regarded internationally as one of the leading markets for floating offshore wind (FLOW), attracting developers, investors and supply chain companies looking to participate in what could become one of the country’s most important energy growth sectors.
Scotland alone has around 14 gigawatts of FLOW projects progressing through the planning system, drawing attention from around the world, not simply to participate in the UK market, but to understand how a floating wind industry can be built at scale.
That potential is real but the sector has entered a critical new phase. The question is no longer whether floating wind works, but whether the conditions exist to deploy it at scale, and those conditions all come back to one thing - certainty.

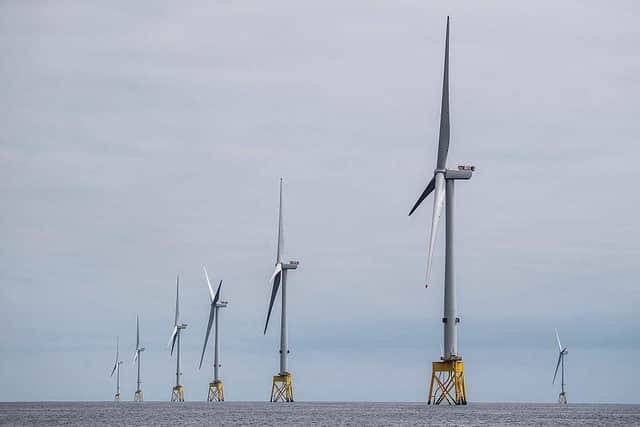
Projects such as Pentland, Erebus and Green Volt are progressing towards final investment decisions and construction. These are no longer demonstration projects in the traditional sense - they will provide the first meaningful evidence of how floating offshore wind performs commercially, from procurement and financing through to construction and operation.
Their successful delivery matters enormously because floating wind is still treated by investors as an emerging asset class. Successful delivery of these first projects could begin to change that, moving the sector towards the position that fixed-bottom offshore wind occupies today as a recognised infrastructure investment class.
As confidence in the technology, construction process and operating performance grows, perceptions of risk should reduce and, in turn, financing costs should fall. Reducing the perception of risk can be every bit as important as reducing the cost of the kit. Certainty itself has economic value.
Many of the mechanisms that will reduce costs require a predictable project pipeline. Ports, fabrication facilities, manufacturing capacity and specialised vessels all require significant upfront investment that cannot sensibly be made on the strength of one or two projects alone. Without confidence in a sustained pipeline, the supply chain cannot develop, costs cannot fall, and the industry cannot reach the scale it needs.
That means looking beyond individual auction rounds and giving developers, investors and the supply chain visibility over a sustained programme of deployment. The concern is not the level of support available today, but whether projects entering development now will encounter a stable and investable market when they are ready to proceed.
The Strategic Spatial Energy Plan, expected next year, represents an important opportunity to provide greater clarity on deployment pathways, grid infrastructure and the role of floating offshore wind within the UK's wider energy strategy.
The UK starts from a genuinely strong position - deep-water sites, decades of fixed-bottom experience, and a sophisticated project finance ecosystem. But that position cannot be taken for granted. Other markets across Europe and Asia are developing their own floating wind ambitions, while the capital, vessels, manufacturing capacity and expertise needed to deliver projects are internationally mobile.
Provide certainty and get the conditions right, and the UK has a credible opportunity not just to build floating wind projects, but to build a floating wind industry.
Niamh Deery, Managing Senior Associate, Pinsent Masons
Comments
Want to join the conversation? Please or to comment on this article.