
Concerns as more families being pulled into IHT net


The UK’s Inheritance Tax (IHT) bill continues to grow, with receipts for April 2025 to March 2026 hitting £8.5 billion, £0.2bn higher than the same period last year.
Experts at the Wealth Club, a non-advisory investment service based in Bristol, have described it as “taxing times for bereaved families”.
It stated that rising receipts come amid intensified enforcement and public criticism that the IHT system is unfairly affecting the middle class – a group historically seen as outside the reach of the duties.
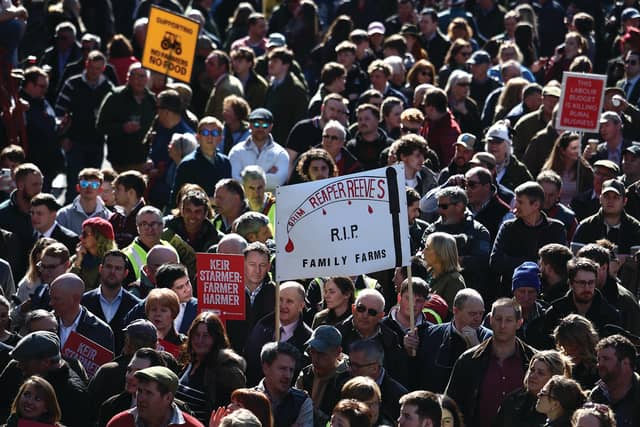
Susannah Streeter, chief investment strategist at the Wealth Club, comments: ‘’The government has arguably made a mess of Inheritance Tax reform. Crackdowns on farmers and business owners proved unpopular and ultimately unworkable, forcing a partial retreat on relief thresholds.
“But years of frozen allowances, combined with new rules that will bring pensions into the scope of IHT, mean more ordinary families, not just the wealthy, are being pulled into the tax net.”
She adds that HMRC’s tougher enforcement is adding further pressure at what is already a difficult time for bereaved families. With the tax base widening and sharp “cliff edges” in the relief system still in place, proactive planning and accurate reporting have never been more important.
According to Susannah, recent reporting also highlights growing frustration that IHT is increasingly affecting middle-income households, particularly those whose wealth is concentrated in property or retirement savings.
Frozen thresholds, unchanged for years, mean more estates are being pulled into liability even without meaningful gains in real-terms wealth.
“Meanwhile, HMRC compliance activity continues to rise. More than 14,000 bereaved families have been investigated for potentially underpaid Inheritance Tax since 2022/23, with case volumes running ahead of last year,” says Susannah.
“These enquiries, often triggered by data matching and valuation checks, can last months or even years and may result in additional tax, interest and penalties.
“Taken together, rising asset values, static allowances and expanding reporting requirements are creating a system that is increasingly out of step with economic reality, drawing in estates that would previously have fallen outside the Inheritance Tax net and catching many families off guard.”
The Wealth Club has set out ways that families and investors can mitigate exposure to IHT:
Susannah says: “Despite tighter rules and increased enforcement, tax-efficient estate planning remains possible, though it now requires earlier and more detailed preparation.
“It’s worth gifting early and carefully. Gifts from surplus income remain immediately exempt, while larger gifts fall outside the estate if the donor survives seven years.
“It might be worth looking at business property relief and qualifying investments. Planning around the £2.5 million relief threshold remains central to reducing exposure.
“AIM ISAs and relief-eligible holdings could be attractive. Certain investment structures may still offer mitigation opportunities, subject to advice and risk assessment.“It’s time to revisit pension strategies. With pensions set to fall within the IHT net from 2027, estate planning around retirement assets is becoming increasingly important.’
Commenting on the latest figures on IHT, Andrew Tully, technical services director at Edinburgh-based Nucleus Financial, says: “IHT receipts have grown by more than 60 per cent over the last five years, a trend that is predicted by OBR [Office for Budget Responsibility] to continue and accelerate. This is due to the freezing of nil-rate bands until April 2031, rising UK property values, and planned reductions to agricultural and business reliefs from April 2026.
“The government is also proceeding with its plans to include pensions within IHT from 6 April, 2027, and the legislation to introduce this was included in the Finance Act 2026 which received Royal Assent on 18 March. This will drive further strong growth in IHT receipts.
“Taken together, all of this is likely to make IHT a more relevant issue for many more families within the next five years. Advisers can help clients mitigate these taxes by setting up trusts and making use of gift allowances and the spousal exemption.
“It is also likely to lead to many people increasing withdrawals from pensions and either spending, gifting or sheltering those amounts.”
Andrew adds that Capital Gains Tax receipts have increased massively by more than 60 per cent on last year, reflecting higher rates and reduced allowances. The big reduction in the annual exemption has left people with less leeway. He concludes: “Advisers can help clients offset losses from other disposals, transfer assets to a spouse or civil partner to use their allowance, stagger sales across tax years, and use ISA and pension wrappers.”
Comments
Want to join the conversation? Please or to comment on this article.