
Springfield Properties slashes debt and launches ‘compelling’ share buyback
“We are disappointed that the market continues to undervalue housebuilders” – chief executive Innes Smith
Scottish housebuilder Springfield Properties has posted lower full-year profits but hailed a strong underlying performance while eliminating its bank debt.
Releasing results for the year to the end of May, Scotland’s only listed homebuilder also confirmed that it intended to commence a share buyback programme as an “effective means to create value for shareholders”.
The group said it had delivered a strong performance over the past year, notwithstanding the “exceptional” prior 12-month period that benefited from significant land sales undertaken as part of the debt reduction strategy.
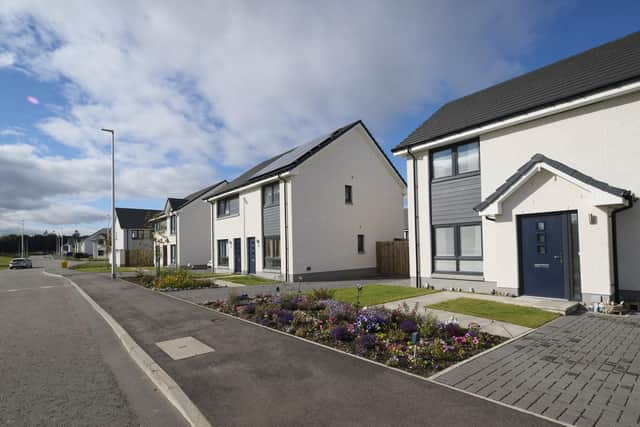

On a statutory basis, Springfield posted a profit before tax of £11.9 million for the full year, down from £19m the previous year, on revenue of £243.7m, down from £280.6m. However, the group noted that it had seen significant year-on-year growth in adjusted profit before tax, when excluding the contribution from land sales in both years.
During the year, it swung from having net bank debt of £20.9m to a cash surplus of £1.2m.
The board is recommending an increased dividend for the year of 3p per share, up from 2p, subject to shareholder approval at the next annual general meeting.
Chief executive Innes Smith said: “This has been an excellent year for Springfield. We achieved a key strategic priority of eliminating our net bank debt, which was significantly ahead of market expectations.
“Our underlying business remained resilient, with year-on-year growth in both private and affordable housing. We made significant progress in capitalising on the substantial opportunities in the north of Scotland, which are being driven by the incoming energy security infrastructure and renewable development.
“Building on our initial agreement to deliver almost 300 homes across six sites for a major infrastructure provider, we have been engaging with our partner as well as progressing works, and we will be signing the main contract for the first site imminently.”
There were a total of 735 completions during the year to May, down from 799 previously. The group said it had delivered revenue growth in private housing thanks to an increase in average selling price, primarily reflecting housing mix. There was a strong performance in affordable housing with revenue growth driven by an increase in completions as well as the average selling price.
Smith added: “Looking to the current year, our private housing reservation rate has been steady and we have continued to secure new contracts on favourable terms in affordable housing. Our significantly strengthened balance sheet has enabled us both to increase our dividend and launch a share buyback programme.
“We are disappointed that the market continues to undervalue housebuilders, with Springfield’s share price remaining materially disconnected from our view of the underlying value of the business, reflecting neither the strength of our balance sheet, the quality of our land holdings or the opportunities available to us in the north of Scotland.
“We therefore see the buyback as a compelling opportunity to create value for shareholders while demonstrating the board’s confidence in Springfield’s future prospects. With strong operational momentum and significant opportunities ahead, we look to the future with confidence.”
Last month, Springfield, which floated on the stock market in 2017, said it had “unlocked value” from its large land bank after selling 170 plots in a £12m milestone deal.
The firm used £6.5m of the proceeds to pay the final consideration for its 2022 acquisition of the Scottish housebuilding business of Mactaggart & Mickel Group. As part of the takeover, there was £30.8m of deferred consideration payable proportionally as homes were sold over five years.
Springfield noted that, as of the end of May, the outstanding deferred consideration was £20.7m, which has now been satisfied.
Smith said: “Two years ago, we set out a clear strategy to unlock value from our substantial land bank through a series of profitable land sales, and this transaction marks the successful completion of that programme.
“As recently announced, we reached a net bank cash position ahead of market expectations. Now, by applying proceeds from this land sale to settle the final Mactaggart & Mickel acquisition payment, we have also completed the deferred consideration significantly ahead of schedule.
“This milestone further strengthens our balance sheet and our position to capitalise on future growth opportunities.”
In February, the group said it was hopeful that lower interest rates and a rebound in consumer confidence would provide a much-needed boost to homebuying as it posted “solid” interim results.
The results for the six months to the end of November 2025 showed that overall revenues were up 2 per cent, year on year, to £108m. Private housing revenue was down 9 per cent at £65.4m while affordable housing revenue grew by 26 per cent to £25.8m. Revenue from land sales almost doubled, up 92 per cent to £9.8m.
Adjusted profit before tax rose 8 per cent to £4.1m though adjusted operating profit was down 13 per cent at £5.6m. Net bank debt fell to £39.6m, from £62.9m a year earlier - a reduction of about 37 per cent.
In a trading update in early June, Springfield told investors that it had removed its bank debt and had a net bank cash position of about £1m - significantly ahead of market expectations.
In 2022, the group struck a £46.3m deal to acquire the housebuilding business of Mactaggart & Mickel in a major consolidation move for the sector in Scotland.
Comments
Want to join the conversation? Please or to comment on this article.